Monday, September 14, 2026

KLA CFO: Export Curbs Cede China Fab Market Share to Rivals

KLA CFO Bren Higgins says US export restrictions block the company from shipping certain semiconductor equipment into some China fabs, while competitors without similar limits keep selling there. KLA's management flags the resulting share loss as a major, high-likelihood risk to its China business and financial guidance.

LM Salvado
LM Salvado

August 3, 2026

KLA CFO: Export Curbs Cede China Fab Market Share to Rivals
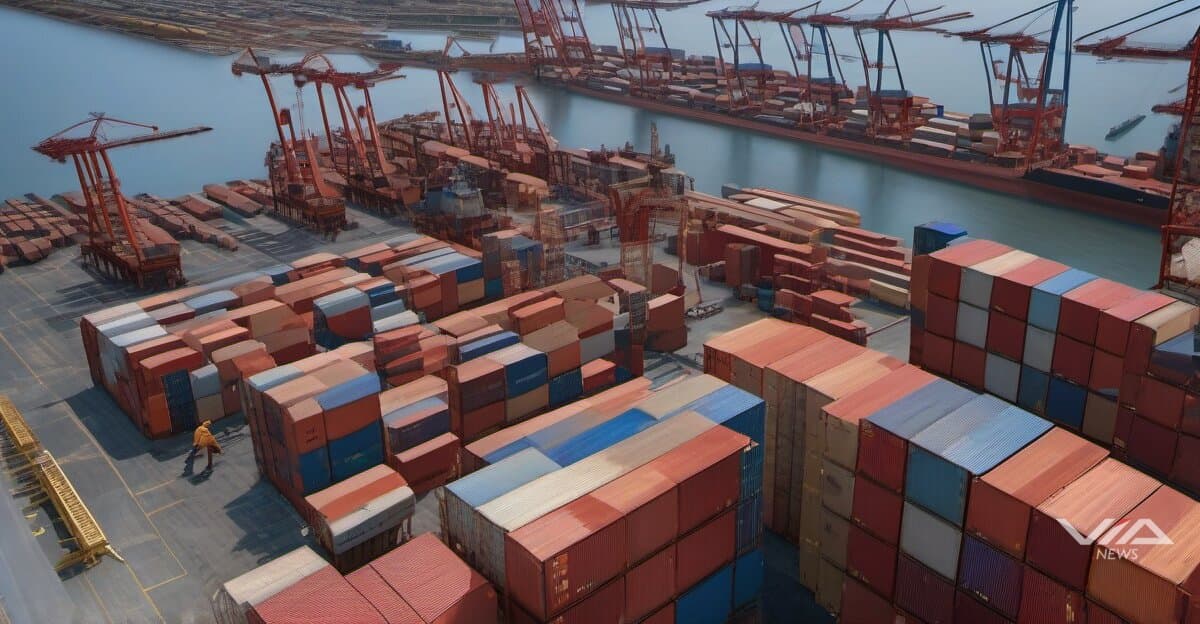
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

KLA Corporation is losing ground in China because US export rules bar it from shipping certain semiconductor equipment into some Chinese fabs, CFO Bren Higgins said while presenting the company's September-quarter guidance.1

Competitors not subject to the same restrictions can still ship equivalent tools into those same fabs, Higgins said. That gap is producing direct share loss in one of KLA's largest markets.1

KLA's own risk assessment rates the exposure "major" in severity and "high" in likelihood, with 0.7 confidence in the finding.2

The mechanism is narrow but costly: it is not a blanket China ban, but a selective license restriction covering specific tool categories destined for specific fabs. Where KLA is blocked, rivals without matching restrictions fill the gap.1

For investors, the distinction matters. A market-wide slowdown would hit every equipment supplier serving China equally. A licensing asymmetry instead reallocates existing demand toward KLA's competitors, converting a policy cost into a direct, quantifiable market-share transfer rather than a shared industry headwind.2

Higgins tied the disclosure to the September-quarter outlook, signaling that Washington's export-control regime is now a standing input to KLA's guidance process rather than a one-time adjustment.1

China has historically been a top revenue source for US semiconductor-equipment makers, and KLA's process-control and inspection tools are used across chip fabrication. Losing access to any subset of that installed base carries recurring revenue implications, since equipment sales are typically followed by service and upgrade contracts.2

The disclosure adds KLA to a group of US chip-equipment suppliers, including Applied Materials and Lam Research, that have flagged China export controls as a drag on results in recent quarters. Unlike broader demand risks, this one is structural: it persists as long as the licensing gap between KLA and its non-US-restricted competitors remains open.2

KLA did not detail the dollar magnitude of the share loss in the disclosed information, and no revised revenue figures tied specifically to the restriction were provided.1
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Network, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI Capital Keeps Flowing as Enterprise Adoption and Government Contracts Validate the Bet
A late-August surge of nine-figure funding rounds (Socure, Stability AI, Generalist AI, Gatik, Regent Craft, Emerald AI, Owner) shows venture capital still pouring into AI infrastructure, identity/fintech, and autonomy, even as public-market sentiment stays jumpy — Palantir's stock fell 6% the same week it landed the Army's TITAN contract. UiPath's raised guidance and strong Q2 results, alongside efficiency breakthroughs like Multiverse Computing's model compression, point to real enterprise monetization catching up to the funding hype.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
JPMorgan Chase & Co.
Both facts record the same attribute (net_income) for JPMorgan Chase & Co. in the identical fiscal period (Q1 2026) and observation date (2026-03-31), but report values that differ by approximately 1 billion times: $16,494,000,000 vs $16.49. These cannot both be true simultaneously. The discrepancy suggests either a unit mismatch (e.g., one is total net income, the other earnings per share mislabeled as net_income), a decimal point error, or data entry corruption. For the same entity, attribute, and time period, only one value can be correct.
We flag conflicts openly ›
Recently verified
Checked against the original source
4,981
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,981 facts checked against source5,285 source documents archived
Query this data → isubstrate.com