Monday, October 12, 2026

Waller Rules Out Nothing: Fed Rate Hikes Return to the Table as Iran War Fuels Inflation

Fed Governor Christopher Waller declared he can no longer rule out rate hikes after Iran War-driven oil prices stalled US disinflation. The hawkish shift — delivered in Frankfurt — has forced markets to rapidly reprice rate expectations. An already fractured FOMC, an ousted Fed chair, and incoming leadership under Kevin Warsh add institutional uncertainty to the policy turmoil.

LM Salvado
LM Salvado

May 26, 2026

Source Trace Score2 source documents2 with a live linkVerifiability: Strong
Waller Rules Out Nothing: Fed Rate Hikes Return to the Table as Iran War Fuels Inflation
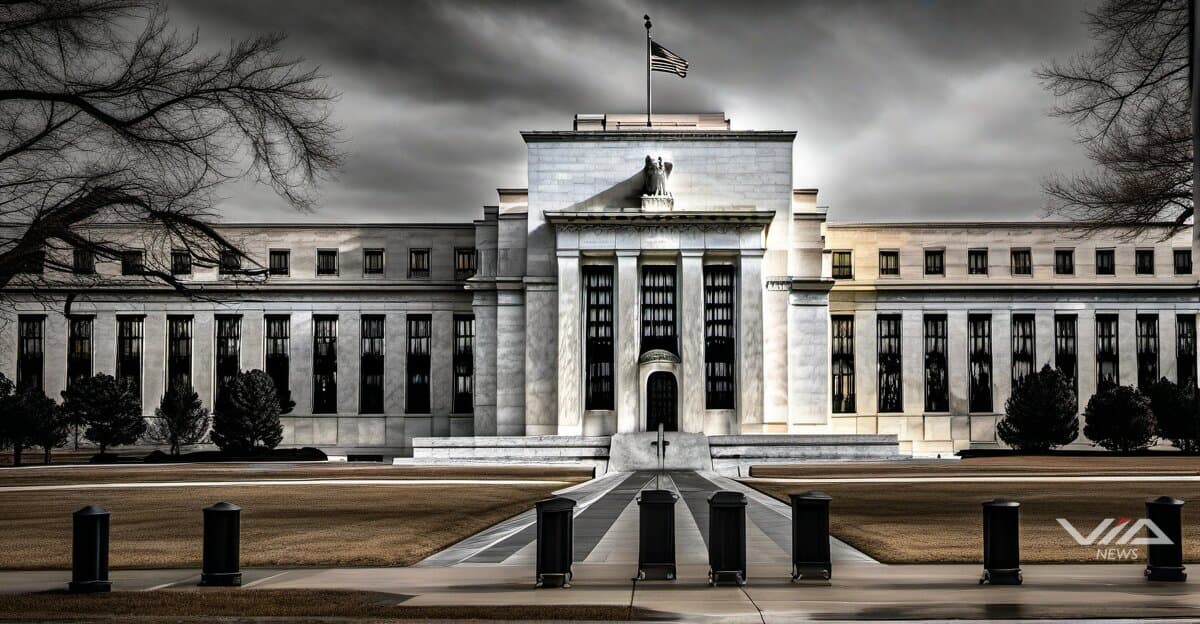
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Fed Governor Christopher Waller issued a direct warning on May 22: rate hikes are back on the table.1 "I can no longer rule out rate hikes further down the road if inflation does not abate soon," Waller said in Frankfurt.1 The statement marks a sharp reversal from the Federal Reserve's prior hold stance.

"Inflation is not headed in the right direction," Waller added.1 Supply-shock inflation triggered by the Iran War — which began in February 2026 — has pushed oil prices higher, disrupting the disinflation path the Fed had been navigating. Waller acknowledged those price pressures could prove temporary if the conflict ends quickly, but said longer-term monetary tightening may be necessary if they don't.1

For now, Waller's stated position is wait-and-see: hold rates steady until the true inflationary impact of the war becomes clearer.1 But markets are no longer pricing that as a stable baseline. Rate-hike probability has been repriced upward following his Frankfurt remarks.

Banking and lending implications

A return to rate hikes would tighten borrowing conditions already strained by elevated long-term yields. Mortgage rates, auto loans, and corporate credit lines would move higher. Banks with floating-rate loan books would benefit from wider net interest margins, but credit quality risks would rise as consumer and business debt-servicing costs climb.

Global investment strategies are adjusting. Higher-for-longer US rates strengthen the dollar, pressuring emerging market debt and commodity importers. Fixed-income allocations face renewed duration risk. Equity valuations — particularly in rate-sensitive sectors like real estate and utilities — come under pressure as the discount rate rises.

Institutional turbulence compounds the risk

The Fed's policy signal arrives amid its worst internal fracture in years. The FOMC's last vote split 8-4, with three formal dissents — an unusually high count reflecting deep disagreement on the path forward.2 A Trump-Powell conflict involving the Justice Department has effectively sidelined Chair Powell, with Kevin Warsh positioned as his replacement.2 Warsh inherits what one report described as a "family fight" over rate cuts at the precise moment cuts are being taken off the table.2

The combination — supply shock inflation, hawkish Fed signaling, and fractured institutional leadership — creates an environment where rate policy is both more consequential and less predictable than at any point in the current tightening cycle.
Source documents

Via News is a conduit. We point to the source documents behind this report — we don't replace them. Trace any claim to its source and decide what to trust. How we source

Source Trace Score2 source documents2 with a live linkVerifiability: Strong
  1. [1]News articleYahoo Finance· May 23, 2026
    Another top Fed official resets rate-cut bets
  2. [2]News articleCNBC· May 16, 2026
    Kevin Warsh comes into the Fed facing a big 'family fight' over cutting interest rates

In this story · Knowledge Files

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Agentic AI Rewires Enterprise Software: Platform Incumbents, Governance, and a Funded Startup Wave
Enterprise software is being rebuilt around autonomous AI agents. Incumbents and large platforms (SAP with its Autonomous Suite and Joule, Zeta with AthenaOS/AIM/Athena MCP, Meta with its new Enterprise Platform) are racing to own the agent layer. Meanwhile, seed and Series A money flows to finance-office and vertical startups (Dextr, Latitude, Dentira, Light), and consolidation continues through acquisitions (Tiny–Oso Cloud, Harvey–Guardrails AI). Investor commentary stresses that AI is better at disrupting around the edges of systems of record than at replacing them, that it should not be trusted with finance calculations, and that governance must be enforced by the system rather than left to agents.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,371 source documents archived
Query this data → isubstrate.com