Tuesday, November 10, 2026

Data Center Power Demand to Rise 165% by 2030, Straining a Grid Built for 1% Annual Growth

Goldman Sachs projects data center electricity consumption will surge 165% by 2030, driven by AI workloads that consume 10x more energy per query than traditional search. The US grid, designed for 1-2% annual demand growth, faces structural scarcity — creating durable pricing power for utilities near major AI data center corridors.

LM Salvado
LM Salvado

June 23, 2026

Data Center Power Demand to Rise 165% by 2030, Straining a Grid Built for 1% Annual Growth
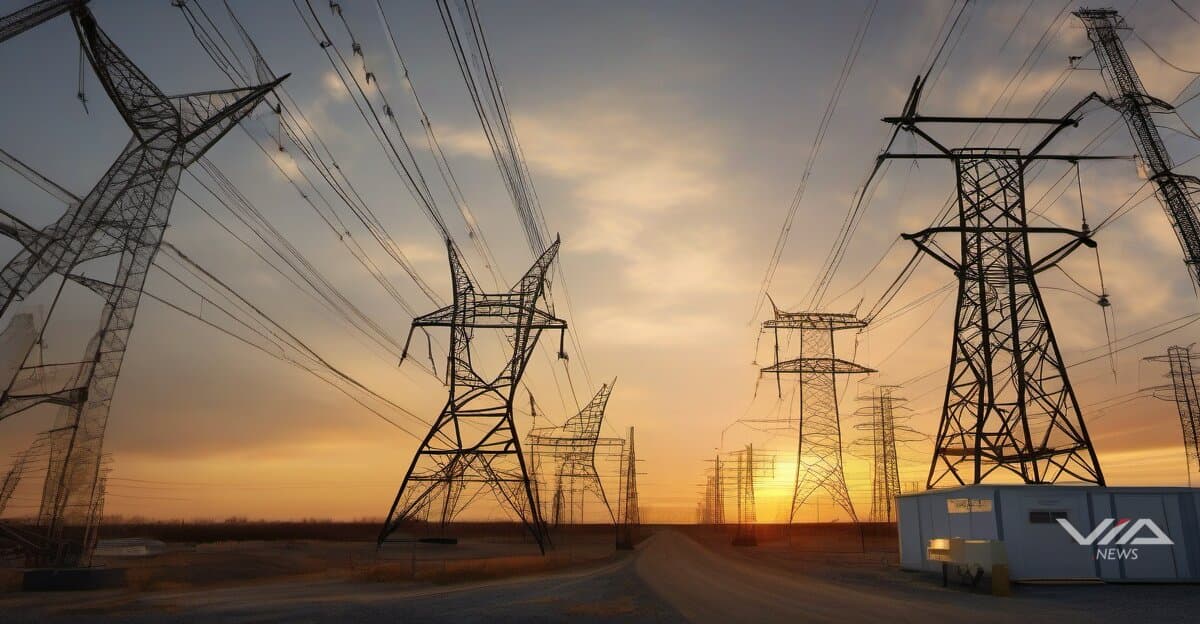
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Data center electricity demand will rise 165% by 2030, according to Goldman Sachs research.1 That single projection is restructuring how institutional investors value US utility and grid infrastructure stocks.

The driver is AI compute. A single ChatGPT query consumes roughly 10 times the energy of a Google search.2 Training next-generation large language models requires power equivalent to small cities.2

Microsoft, Amazon, and Alphabet are among the largest consumers on the US electricity grid.2 Their data center energy demand is structurally price-inelastic — compute must run regardless of power costs. That dynamic is fundamentally different from residential or commercial electricity demand, which responds to price signals.

The US grid was engineered for 1-2% annual demand growth.2 That design assumption is now a binding constraint. Existing grid-connected generation capacity near major data center hubs carries scarcity value that utilities did not price into long-term planning.

Power purchase agreements (PPAs) with AI hyperscalers are emerging as the key earnings quality metric for utility investors. Utilities that executed long-term supply contracts before the AI demand surge — particularly those with generation assets near Northern Virginia, Phoenix, Chicago, and Dallas data center corridors — carry the strongest forward earnings visibility.

Bitzero Holdings (AIBZ) is among the companies targeting this infrastructure intersection.2 The investment thesis: proximity to AI workload demand creates a recurring, durable revenue base that traditional industrial or residential customers cannot replicate.

Capacity factor utilization is the operational signal to watch. Grid-connected generation near high-density compute clusters runs at higher utilization rates, compressing unit economics and improving asset returns over time.

The primary risk is regulatory lag. US utility rate structures were not designed for large industrial AI customers. Interconnection queues and cost-allocation frameworks are under review in multiple states as grid strain increases — adding permitting uncertainty to new capacity build-out timelines.

Goldman Sachs projects 165% data center power demand growth through 2030.1 That implies a structural shift in who the marginal electricity buyer is. Utilities near established AI infrastructure corridors, with contracted supply agreements in place, are the direct beneficiaries of that shift.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Biotech Catalyst Cycle: Data Readouts, FDA Decisions and Capital-Allocation Shifts
From late October to January, mid-cap biotechs move through a dense run of events: ESMO and AHA/AASLD data presentations, Q3 earnings, and FDA PDUFA dates for ivonescimab (Nov 14) and lorundrostat (Dec 22). Alongside the regulatory news, companies are changing how they allocate capital: one lowered FY2026 R&D and SG&A guidance and pushed milestones into 2027, one authorized a $400M buyback, and one scheduled a delisting vote (EGM Nov 19, application Jan 25). Value is concentrating in a few binary regulatory and Phase 3 outcomes (Maritime-1 and ECLIPSE 2/3 readouts around Q1 2027), so sentiment is mixed.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Ford Motor Company
Both facts give cash for Ford Motor Company at the same point in time (2025-12-31; FY 2025 year-end and Q4 2025 year-end are the same date). Both are labelled USD, but the values are 23,356,000,000 and 23.356, which cannot both be true in USD. The two numbers agree once the second is read as billions (23.356 bn = 23,356,000,000), so the economic content is consistent and the conflict is a unit/scale error in the Q4 2025 record. The period is not the reason for the conflict: a Q4 and an FY figure at the same year-end date should match.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,996
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,996 facts checked against source5,558 source documents archived
Query this data → isubstrate.com