Friday, October 2, 2026

Gulfport's Utica Deal Prices Acreage at $17,500/Acre, Betting on Gas Prices That May Not Hold

Gulfport Energy Corporation's newly acquired Utica shale acreage carries an implied valuation of roughly $17,500 per net acre and $5.1 million per net location, economics that depend on natural gas and NGL prices staying high enough to justify 15,000-foot lateral wells. Analysts flag a major, medium-likelihood risk: a sustained downturn in Utica gas or NGL pricing could impair the asset before it produces a barrel.

LM Salvado
LM Salvado

July 3, 2026

Gulfport's Utica Deal Prices Acreage at $17,500/Acre, Betting on Gas Prices That May Not Hold
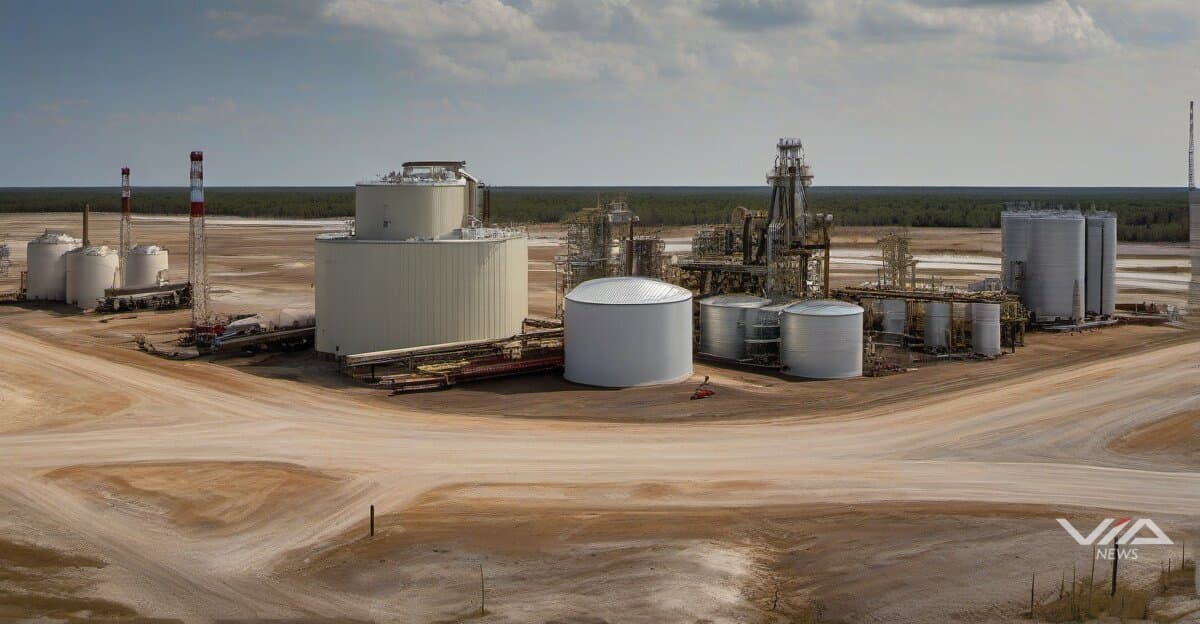
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Gulfport Energy Corporation's latest Utica shale acquisition is priced at roughly significant capitalper net acre, or about millions per net location.1 That valuation assumes natural gas and NGL prices hold high enough to justify developing 15,000-foot laterals, the long-reach drilling needed to make the deal's economics work.1

The risk: a sustained slide in Utica gas or NGL pricing could turn the acquisition into an impaired asset before first production.1 Analysts rate the exposure a major-severity, medium-likelihood risk, with 0.7 confidence in the assessment.1

Gulfport is an Oklahoma City-based operator focused on Utica shale development in eastern Ohio, where it holds liquids-rich gas acreage.1 The company's growth strategy leans on acquiring adjacent acreage and stretching lateral lengths to cut per-well costs and boost recovery. Longer laterals require more upfront capital, which raises the stakes if commodity prices move against the deal before wells are drilled and turned to sales.

The Utica play produces both dry natural gas and natural gas liquids, meaning the acquisition's returns hinge on two separate price tracks rather than one. NGL prices tend to move with oil markets, while natural gas prices are driven by domestic supply and demand, particularly LNG export demand and power-sector consumption. A downturn in either commodity, or both together, would compress the netbacks needed to justify the deal's per-acre price tag.

Because the valuation was set before any wells on the new acreage are drilled, the acquisition carries a lag between capital deployment and cash flow. If gas or NGL prices fall during that window, Gulfport could be forced to book an impairment on acreage it has not yet produced from, a scenario that would pressure the balance sheet without any offsetting output.

The deal underscores a broader dynamic across Utica operators: acreage valuations set during periods of firm gas pricing can become vulnerable quickly if the commodity cycle turns before drilling catches up.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI-Driven Drug Development Meets Biotech Deal-Making and Regulatory Catalysts
AI-designed therapeutics (Insilico's rentosertib showing biological-age reductions) are moving into the clinical mainstream. Large-cap biotech is simultaneously reallocating capital through M&A (Lilly–Merida, $2.9B) and government funding (BARDA–Basilea), while trial failures (ziltivekimab, a 9.4% Novo Nordisk share drop) and upcoming FDA catalysts (the ivonescimab PDUFA on 2026-11-14) drive volatility. The wider AI regulatory and legal climate (Tesla Cybercab probe, xAI's Minnesota loss, OpenAI suits) is tightening, though QAIAx's micro-cap trial claims are speculative and weakly connected.
Our read on the data ›
Signals we're tracking
Satellite-Terrestrial Network Integration Acceleration
Increased investment and launches in hybrid satellite-cellular networks across telecom industry; competitive responses from other carriers; regulatory activity around satellite spectrum; expansion of emergency/rural connectivity use cases
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,985
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,985 facts checked against source5,327 source documents archived
Query this data → isubstrate.com