Friday, October 2, 2026

Automakers Race to Deploy Level 2++ Systems Across Vehicle Lineups as 2025-2026 Launch Window Opens

Multiple vehicle manufacturers are preparing to launch Level 2++ autonomous driving systems as standard features across their lineups in 2025-2026. The deployment wave aims to expose consumers to advanced driver assistance at scale while generating real-world training data for higher autonomy levels.

LM Salvado
LM Salvado

March 19, 2026

Automakers Race to Deploy Level 2++ Systems Across Vehicle Lineups as 2025-2026 Launch Window Opens
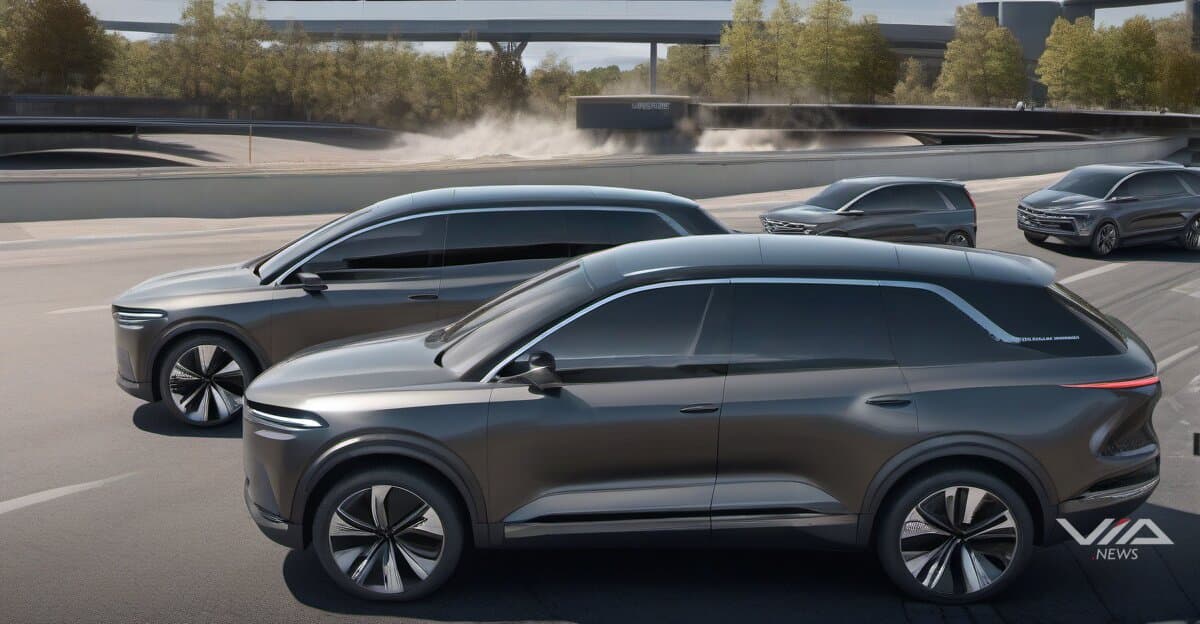
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Automakers are accelerating Level 2++ autonomous driving system deployments across multiple vehicle lines, with launches concentrated in the 2025-2026 window. The systems represent an intermediate step between basic driver assistance and full autonomy, handling steering, acceleration, and braking under driver supervision.

The commercialization push shifts Level 2++ from premium options to standard equipment. Vehicle manufacturers are positioning these systems as baseline features rather than luxury add-ons, expanding the addressable market beyond early adopters.

The deployment strategy serves dual purposes for OEMs. Consumer exposure to autonomous capabilities builds familiarity and trust in the technology. Simultaneously, the installed fleet generates training data at scale, feeding machine learning models for Level 3 and Level 4 development.

Competition centers on which manufacturers can achieve the widest deployment fastest. First movers gain data advantages—more vehicles on roads means more edge cases captured, more scenarios processed, and faster iteration cycles. This creates pressure on laggards to match deployment timelines or risk falling behind in both market share and technical capability.

The automotive industry faces a coordination problem. Level 2++ adoption requires consumer education, regulatory clarity, and infrastructure preparation. Manufacturers deploying early shoulder higher education costs but establish market position. Later entrants benefit from prepared markets but cede data collection advantages.

Investment implications turn on execution speed and scale. Companies delivering robust Level 2++ systems across volume segments by 2026 position themselves for the autonomous vehicle transition. Those limiting deployments to flagship models or missing the launch window face compounding disadvantages as competitors accumulate operational data.

The 2025-2026 timeframe represents a bottleneck. Production capacity, supplier readiness, and regulatory approval processes constrain how many vehicles can launch with Level 2++ systems. Winners in this window gain market and technical advantages that compound over subsequent development cycles.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI-Driven Drug Development Meets Biotech Deal-Making and Regulatory Catalysts
AI-designed therapeutics (Insilico's rentosertib showing biological-age reductions) are moving into the clinical mainstream. Large-cap biotech is simultaneously reallocating capital through M&A (Lilly–Merida, $2.9B) and government funding (BARDA–Basilea), while trial failures (ziltivekimab, a 9.4% Novo Nordisk share drop) and upcoming FDA catalysts (the ivonescimab PDUFA on 2026-11-14) drive volatility. The wider AI regulatory and legal climate (Tesla Cybercab probe, xAI's Minnesota loss, OpenAI suits) is tightening, though QAIAx's micro-cap trial claims are speculative and weakly connected.
Our read on the data ›
Signals we're tracking
Satellite-Terrestrial Network Integration Acceleration
Increased investment and launches in hybrid satellite-cellular networks across telecom industry; competitive responses from other carriers; regulatory activity around satellite spectrum; expansion of emergency/rural connectivity use cases
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,985
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,985 facts checked against source5,327 source documents archived
Query this data → isubstrate.com
Automakers Race to Deploy Level 2++ Systems Across Vehicle Lineups as 2025-2026 Launch Window Opens | Finance Via News