Saturday, October 10, 2026

Nvidia Acquires Groq as AI Chip Industry Moves to Vertical Integration

Nvidia has acquired Groq, maker of Language Processing Units, as the AI silicon supply chain consolidates across multiple simultaneous deals. Broadcom is co-developing custom processors with both OpenAI/Arm and Alphabet, while Tiger Global has increased stakes in Nvidia, Broadcom, and TSMC simultaneously. Custom silicon players are expected to widen their competitive moat as commodity GPU revenue faces pressure within 18–24 months.

LM Salvado
LM Salvado

May 25, 2026

Nvidia Acquires Groq as AI Chip Industry Moves to Vertical Integration
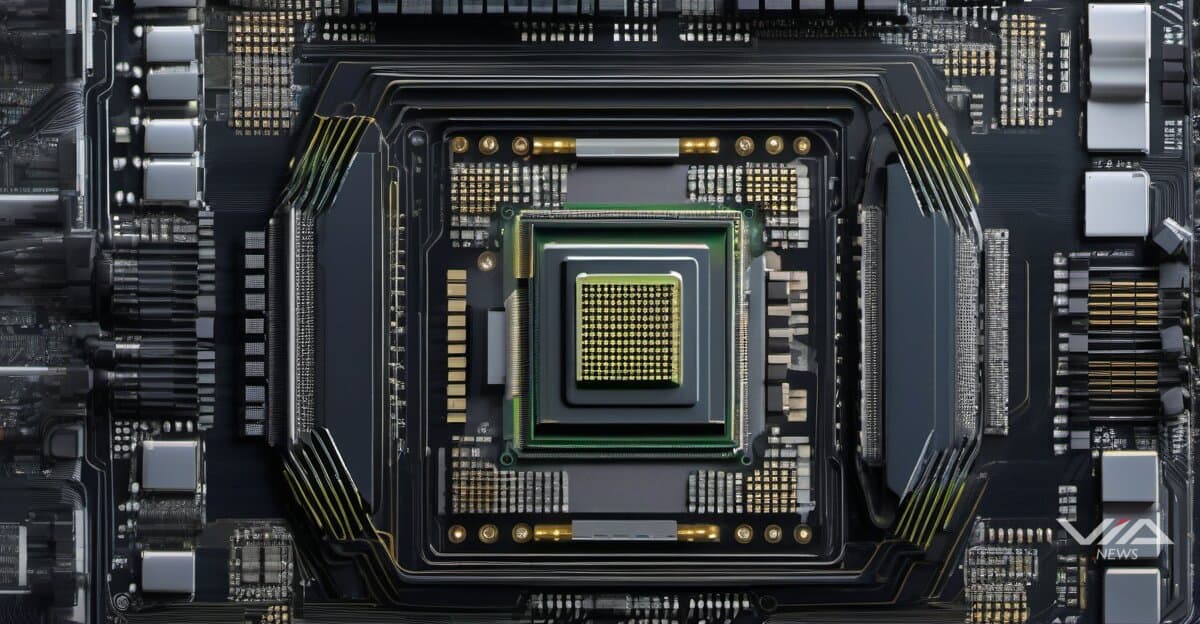
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Nvidia has acquired Groq, the startup behind Language Processing Units (LPUs), in a move that accelerates vertical integration across the AI chip industry.1 The deal arrives alongside a cluster of parallel partnerships reshaping who controls AI compute.

Broadcom is collaborating with Arm and OpenAI on custom processor development, while separately co-developing TPUs with Alphabet.1 Nvidia is also shipping Vera CPUs, extending its footprint beyond GPUs into central processing.1

Tiger Global has increased positions in Nvidia, Broadcom, and TSMC simultaneously — a coordinated bet across chip design and manufacturing.1

The common thread across all these moves: hyperscalers are reducing dependence on commodity GPU purchasing. Instead of buying general-purpose chips, the largest AI buyers are now co-designing or acquiring the silicon itself.

This shift has a direct financial implication. Custom silicon players are building durable competitive advantages — each proprietary chip deepens the switching cost for the customer that co-designed it. Groq's LPU architecture, optimized for inference throughput rather than training, fits a specific and growing workload profile that Nvidia now controls end-to-end.

For Broadcom, the dual partnerships with OpenAI and Alphabet cement its role as the preferred custom ASIC partner for hyperscalers unwilling to build full in-house chip teams. TSMC sits at the center of all manufacturing, explaining Tiger Global's simultaneous position-building.

Analysts tracking the sector expect commoditization pressure on general-purpose GPU revenue to materialize within 18 to 24 months as custom silicon deployments scale.1 The transition does not eliminate Nvidia's dominance in the near term — it redirects it. Owning Groq's inference-optimized architecture gives Nvidia a product for customers who find standard GPUs over-engineered for deployment workloads.

The consolidation wave reflects a broader financial logic: in AI infrastructure, vertical integration compresses margin leakage and locks in revenue across the stack. Every layer captured — from chip architecture to runtime software — is a layer competitors cannot monetize.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Agentic Enterprise Software Consolidates: Big Platforms Push Autonomy While Startups Get Absorbed
Enterprise software is shifting toward autonomous, AI-agent-driven products. SAP (Autonomous Enterprise, Joule), Meta (a new Enterprise Platform led by ex-MongoDB CEO Chirantan Desai) and UiPath (raised guidance) are pushing from the top. Meanwhile AI-security and governance startups are being acquired (Fortinet–Virtue AI, Harvey–Guardrails AI, Tiny–Oso Cloud) and seed-stage agent companies keep raising capital (Dextr, Latitude, Groq). Investors such as Norwest's Sean Jacobsohn see finance and ERP back-office software as the easier area to disrupt. Trust and enforced governance are treated as preconditions for regulated sectors like finance, and AI is judged unreliable for calculations.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,366 source documents archived
Query this data → isubstrate.com