Tuesday, November 10, 2026

70% Grid Rejection Rate Puts $5.2T AI Data Center Capex Buildout at Risk Through 2030

More than 70% of US grid interconnection requests are withdrawn due to capacity constraints, threatening a $5.2 trillion AI data center investment cycle. Goldman Sachs projects global data center power demand to surge 165% by 2030 — against a grid built for 1-2% annual growth. Hyperscalers face a widening gap between announced capex and deployable capacity.

LM Salvado
LM Salvado

June 23, 2026

70% Grid Rejection Rate Puts $5.2T AI Data Center Capex Buildout at Risk Through 2030
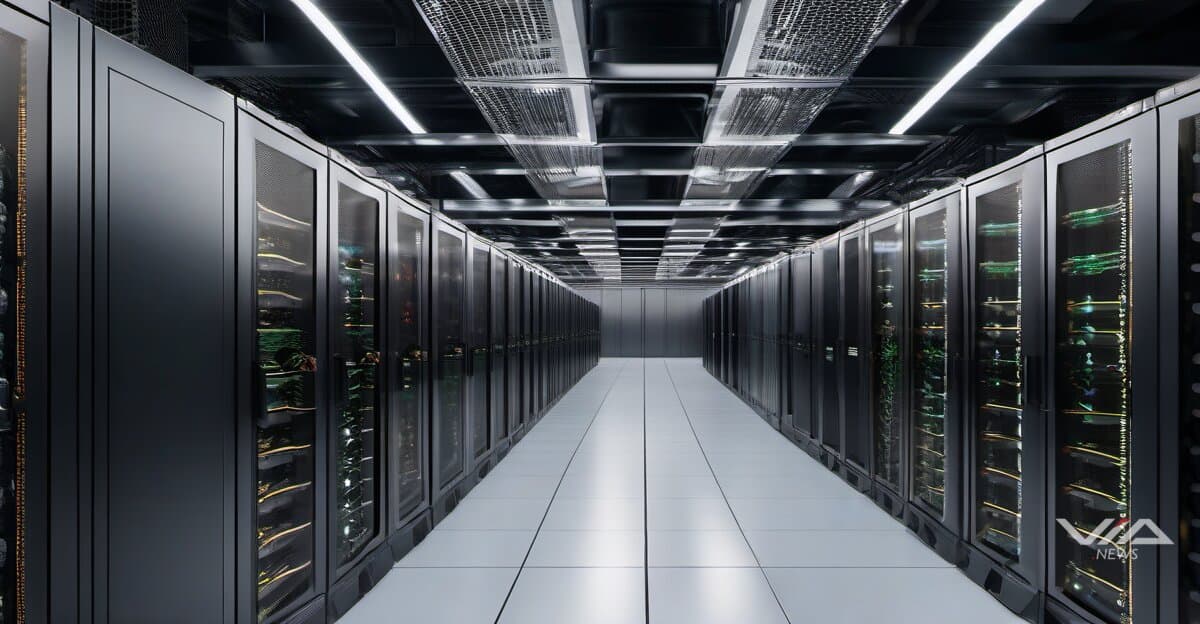
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

More than 70% of US grid interconnection requests are ultimately withdrawn due to capacity constraints, according to Berkeley Lab data.1 That bottleneck now sits at the center of a $5.2 trillion AI data center investment cycle — and threatens to compress returns for the hyperscalers funding it.2

Goldman Sachs projects global data center power demand will surge 165% by 2030 versus 2023 levels.3 The US power grid was designed for 1-2% annual demand growth. The gap between those two trajectories is where hyperscaler capex plans collide with physical reality.

Microsoft, Amazon, and Alphabet have each signaled multi-hundred-billion-dollar infrastructure commitments in recent quarters. But committed capex and deployed capacity are not the same thing. When interconnection queues stall or collapse — which Berkeley Lab data shows they do at a 70%-plus rate — announced projects become stranded capital.1

Investor Kevin O'Leary has argued that 50% of planned US data centers will never be built due to grid constraints.4 Even at lower failure rates, the arithmetic affects financial models. A 30-50% curtailment of the $5.2 trillion buildout redirects capital without producing proportional revenue-generating assets.2

The financial risk compounds across the supply chain. Hyperscalers booking land, signing power purchase agreements, and ordering hardware before interconnection approval creates cost exposure that precedes any revenue. If projects cancel post-commitment, write-downs follow.

Investors monitoring hyperscaler earnings should track divergence between capex guidance and actual data center commissioning rates. FERC interconnection queue approval rates are a leading indicator. When withdrawal rates hold above 70%, the probability of announced buildout milestones slipping increases materially.1

The US grid's structural limitations are not temporary. Upgrading transmission infrastructure takes 5-10 years under normal regulatory timelines. AI demand is accelerating now. That mismatch creates a sustained headwind for capex-to-capacity conversion rates through at least 2030.

Hyperscalers with diversified geographic exposure — including European and Asian grid markets — carry less concentration risk. Those weighted heavily toward US buildout face the highest exposure to interconnection bottlenecks.1

The $5.2 trillion figure represents announced intent, not guaranteed deployment.2 Grid physics may prove to be the binding constraint that financial models have not yet fully priced.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Biotech Catalyst Cycle: Data Readouts, FDA Decisions and Capital-Allocation Shifts
From late October to January, mid-cap biotechs move through a dense run of events: ESMO and AHA/AASLD data presentations, Q3 earnings, and FDA PDUFA dates for ivonescimab (Nov 14) and lorundrostat (Dec 22). Alongside the regulatory news, companies are changing how they allocate capital: one lowered FY2026 R&D and SG&A guidance and pushed milestones into 2027, one authorized a $400M buyback, and one scheduled a delisting vote (EGM Nov 19, application Jan 25). Value is concentrating in a few binary regulatory and Phase 3 outcomes (Maritime-1 and ECLIPSE 2/3 readouts around Q1 2027), so sentiment is mixed.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Ford Motor Company
Both facts give cash for Ford Motor Company at the same point in time (2025-12-31; FY 2025 year-end and Q4 2025 year-end are the same date). Both are labelled USD, but the values are 23,356,000,000 and 23.356, which cannot both be true in USD. The two numbers agree once the second is read as billions (23.356 bn = 23,356,000,000), so the economic content is consistent and the conflict is a unit/scale error in the Q4 2025 record. The period is not the reason for the conflict: a Q4 and an FY figure at the same year-end date should match.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,996
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,996 facts checked against source5,558 source documents archived
Query this data → isubstrate.com